
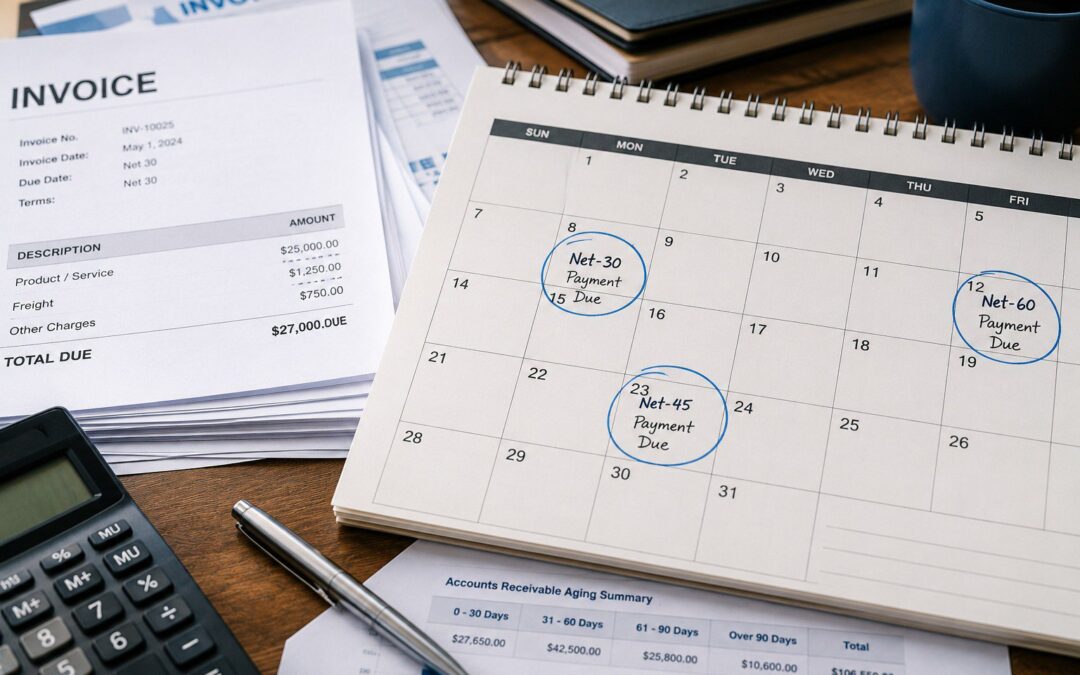
Net payment terms decide when cash leaves the buyer and when it lands in the vendor's account, shaping working capital on both sides of every transaction. According to J.P. Morgan, shifting from net 30 to net 60 lets buyers hold cash twice as long, extending days payable outstanding. Vendors feel the mirror image of that shift as extended days sales outstanding.
Choosing terms without modeling the cash flow impact often leads to gaps between when vendors ship and when they get paid. You will see how each net term shapes vendor cash flow, receivables risk, and working capital needs. You will also see which financing tools bridge the gap without forcing a term renegotiation.
What Do Net-30, Net-45, and Net-60 Actually Mean?
Net-30, net-45, and net-60 refer to the number of days a buyer has to pay an invoice after issuance or delivery. Each additional day extends how long the vendor waits for cash and how long the buyer holds it. Terms directly shape days sales outstanding (DSO), working capital needs, and receivables risk for both parties.
How Each Net Payment Term Reshapes Vendor Cash Flow
Net-30 remains the default across most B2B industries and keeps the cash conversion cycle relatively short. Vendors ship goods or deliver services, invoice on delivery, and expect payment within 30 calendar days. Meanwhile, net-45 and net-60 push that window further out, doubling the working capital vendors need to bridge the gap.
According to Phoenix Strategy Group, 60 percent of US small businesses report cash flow issues tied to late payments or extended terms. The same source notes that optimizing payment terms can unlock 5 to 10 percent of working capital for larger organizations. As a result, term selection has direct financial consequences for vendors of any size.
Consider how net payment terms map to vendor cash flow requirements at a simple revenue level:
- Net-30 on $100,000 monthly revenue creates roughly $100,000 in outstanding receivables.
- Net-45 on the same revenue creates roughly $150,000 in outstanding receivables.
- Net-60 doubles the exposure to about $200,000, plus buffer for late payers.
- Every additional 15 days requires proportionally more working capital to cover payroll and suppliers.
In addition, terms often stretch beyond their stated windows because buyers pay late by habit or process delay. See our blog on receivables tools for related planning notes. You can also review the how it works page for adjacent options.
Why Buyers Push for Longer Terms and What Vendors Give Up

Large buyers routinely request net-60 or net-90 because longer terms fund their own working capital at no interest cost. According to Corpay, net-60 improves the buyer's days payable outstanding and frees working capital, but it raises the seller's DSO and receivables risk. Consequently, vendors trade cash flow for the ability to keep or win the account.
Concessions can come in many forms, and skilled negotiators structure trade-offs rather than accepting flat term extensions. Some vendors accept longer terms in exchange for larger order volumes, longer contract commitments, or price increases that offset carrying costs. Meanwhile, others offer early payment discounts such as 2/10 net-30 to speed collections without formally shortening the term.
Consider the trade-offs vendors face when a buyer asks to extend net payment terms:
- Higher working capital needs that may require a line of credit draw.
- Increased receivables risk if the buyer's credit deteriorates during the extended window.
- Reduced ability to reinvest cash in inventory, payroll, or growth spending.
- Compressed margins if financing costs offset the value of the retained account.
Also, mismatched terms across your customer base create forecasting blind spots. Review the seller page for tools that shorten the cash conversion cycle without a term change.
Modeling the True Cost of Extended Terms
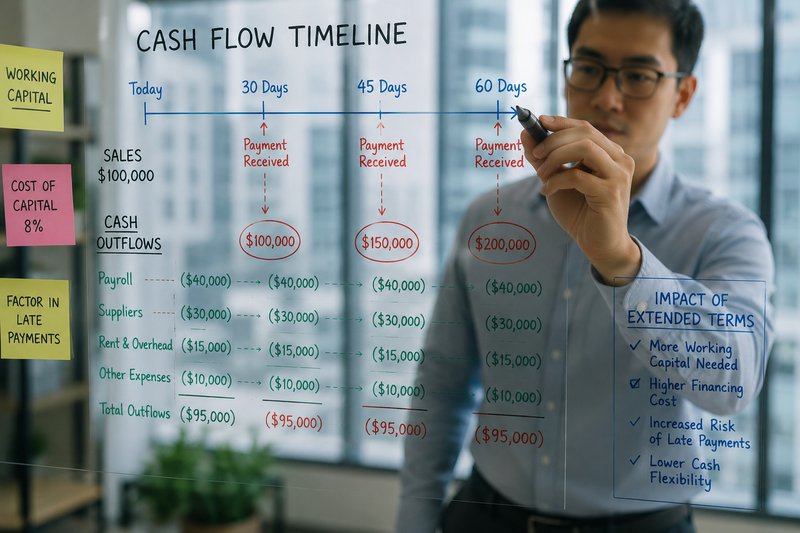
Every additional day of net payment terms carries a carrying cost tied to your cost of capital. A $50,000 invoice on net-30 at an 8 percent cost of capital costs roughly $329 in financing charges over the payment window. Meanwhile, the same invoice on net-60 doubles that carrying cost before considering late payment risk.
Late payment probability also rises with longer terms because more time passes between delivery and collection. Vendors offering net-60 often see actual payment at 75 to 90 days, which extends the true DSO further. As a result, the stated term understates the working capital burden vendors carry in practice.
Modeling both stated and actual DSO by customer segment reveals where terms hurt margin most. Additionally, segmenting customers by credit risk shows where non-recourse tools could shift bad-debt exposure off your books. Review the electronic payments page for tools that accelerate settlement across customer segments.
Bridging the Gap Without Renegotiating Terms
Vendors often cannot shorten net payment terms without losing accounts, so bridging tools become the practical alternative. Buyer-funded early pay lets the buyer approve an invoice while the vendor receives payment within 24 hours. Meanwhile, the buyer keeps or extends the original term, which preserves the account relationship.
Dynamic discounting works on a sliding scale where the discount shrinks as the invoice ages toward its due date. Reverse factoring and supply chain finance platforms achieve similar economics through third party funding. As a result, vendors can maintain long terms on paper while collecting cash on a much shorter cycle in practice.
Cross-border vendors and freight carriers use these tools alongside traditional bank lines. Review the international buyer page and the freight broker page for sector examples.
Ready to Manage Net Terms Without Draining Cash Flow?
Net payment terms shape vendor cash flow more than any single line item on the income statement, and small term changes compound into large working capital swings. Modeling stated and actual DSO by customer segment reveals where longer terms hurt margin most. Bridging tools then let vendors keep the account while shortening the effective cash conversion cycle.
Our team helps vendors and buyers structure working capital that fits alongside existing net terms and bank facilities. We fund domestic and international invoices without filing UCCs or taking security interests in your assets. To review your options, please set up a call with our team for a cash flow assessment.
