
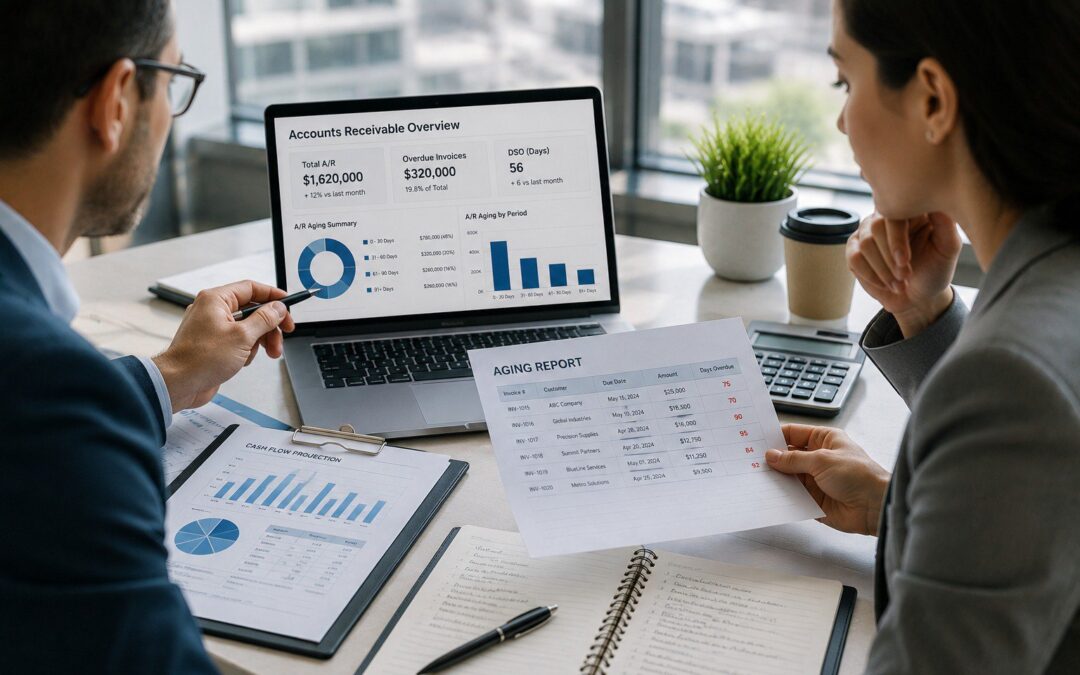
Late customer payments have shifted from exception to norm, and invoice factoring gives suppliers a way to convert unpaid invoices into cash within days. According to Allianz Trade, average days sales outstanding (DSO) rose to 59 days in 2023, with one in five companies waiting more than 90 days. Waiting that long strains payroll, supplier payments, and growth spending.
Factoring works by selling receivables to a third party who advances cash upfront and collects from your customer later. You will see how the mechanics work, what factoring costs, and where it fits alongside other working capital tools. You will also see when unsecured alternatives may cost less.
How Does Invoice Factoring Help With Slow Payments?
Invoice factoring converts unpaid receivables into cash within 24 to 48 hours by selling them to a factor at a small discount. The factor advances 80 to 90 percent of face value, collects from your customer, and releases the balance minus a fee. The result is predictable cash flow without waiting for net 30, 60, or 90 day terms to close.
How the Invoice Factoring Process Actually Works
Factoring starts when you submit an invoice to the factoring company, which verifies the receivable and advances an agreed percentage. The factor then takes responsibility for collecting payment from your customer under the invoice's original terms. Once the customer pays, the factor releases the reserve balance to you minus its fee.
Advance rates typically fall between 80 and 90 percent of face value, and fees run 1 to 3 percent per invoice cycle. Meanwhile, funding usually arrives within one to two business days of invoice verification. Setup takes longer, since factors run credit checks on your customers and negotiate the master factoring agreement.

Consider the operational steps that make up a standard invoice factoring cycle:
- Submit approved invoices to the factor through a portal or file upload.
- Factor verifies the invoice with your customer and confirms delivery of goods or services.
- Factor advances the agreed percentage into your operating account within 24 to 48 hours.
- Customer pays the factor directly on the original due date.
- Factor releases the reserve balance minus fees once payment clears.
Furthermore, factoring can be recourse or non-recourse depending on who absorbs the loss if the customer never pays. See our blog on receivables tools for related planning notes. You can also review the how it works page for adjacent options.
The True Cost of Slow Customer Payments
Late payments carry costs that extend well beyond the invoice amount itself. Payroll gets funded from reserves, suppliers push for prepayment, and growth spending stalls while receivables age. According to Kapittx, US companies write off an average of 3 to 5 percent of B2B invoices as bad debts each year.
Working capital tied up in aging receivables cannot fund inventory, marketing, or new hires. Meanwhile, invoices older than six months carry a 70 percent probability of becoming uncollectible per the same source. Consequently, the longer you wait, the more likely the receivable turns into a write off rather than cash.
Invoice factoring shifts that risk profile in two ways at once. First, it accelerates the cash conversion cycle so working capital returns to the operating account faster. Second, non-recourse structures transfer some or all of the bad debt risk to the factor.
Review the seller page for tools built around supplier receivables.
When Factoring Fits and When It Does Not

Factoring works well for suppliers with creditworthy customers and long payment terms, but the fit depends on volume and margin. Companies with thin margins may find factoring fees erode too much of the invoice value. Meanwhile, businesses with strong customer concentration face discounts because factors limit exposure to any single buyer.
Recourse structures shift bad debt risk back to you if the customer fails to pay within an agreed window. Non-recourse structures cost more but protect the receivable against buyer insolvency. Read every clause carefully, since the terms drive the actual economics rather than the headline advance rate.
Consider these questions before signing a factoring agreement:
- Do your customers have strong credit ratings that support high advance rates?
- Is your margin large enough to absorb 1 to 3 percent per invoice cycle?
- Can you accept the factor contacting your customers directly for verification and collection?
- Does the agreement include monthly minimums or long-term commitments?
It is also worth noting that some factors require a UCC-1 filing against your receivables that may conflict with existing lenders. See our blog on funding around active liens for related detail.
Comparing Factoring to Unsecured Early Pay
Factoring is not the only way to convert invoices into cash quickly. Buyer-funded early pay platforms achieve a similar result without a UCC filing or a formal factoring agreement. The buyer approves the invoice, the platform pays you within 24 hours, and the buyer settles on extended terms.
Because the buyer funds the discount, invoice factoring fees do not come out of your margin in the same way. Meanwhile, non-recourse structures still protect you against buyer nonpayment. As a result, suppliers with buyer-approved invoices often find early pay cheaper than a factoring facility.
Cross-border suppliers, freight carriers, and mid-market vendors use early pay alongside traditional lines. Review the international buyer page and the freight broker page for sector examples.
Ready to Solve Slow Customer Payments?
Slow customer payments cost more than the fees on any single financing product, and the right tool depends on your customer mix, margin, and lender relationships. Invoice factoring works well for suppliers with creditworthy customers and enough margin to absorb the discount. Unsecured early pay often costs less when your buyer is willing to participate.
Our team helps suppliers structure working capital that fits alongside existing bank lines and factoring facilities. We fund domestic and international invoices without filing UCCs or taking security interests in your assets. To review your options, please request a working capital review with our team.
