
Business-to-business (B2B) transactions run on credit terms, deferred payments, and layered supplier relationships, and commercial financing solutions decide whether that structure creates growth or friction. Suppliers extend net 30, 60, or 90-day terms while covering payroll and inventory upfront. According to Global Finance, the global supply chain finance market reached $7.5 billion in 2024, driven by rising demand for working capital tools.
B2B companies now have access to a broader product set than the traditional line of credit or factoring facility. You will see how trade credit insurance, reverse factoring, purchase order financing, and buyer funded early pay each solve different B2B problems. You will also see where these tools overlap and where they compete.
Which Commercial Financing Solutions Fit B2B Companies Best?
The right fit depends on whether you sit on the buyer side, the supplier side, or both in a transaction. Buyers often use reverse factoring, purchase card programs, and trade credit lines to extend terms while paying suppliers early. Suppliers use invoice financing, purchase order funding, and buyer funded early pay to accelerate cash from approved invoices.
Reverse Factoring and Buyer Led Supply Chain Finance
Reverse factoring flips the traditional factoring model by having the buyer initiate the program rather than the supplier. The buyer partners with a financial institution or platform that pays approved invoices early at a discount tied to the buyer's credit rating. Meanwhile, the buyer settles with the platform on extended terms, which improves both parties' working capital.
According to Research Nester, the global reverse factoring market reached USD 673.27 billion in 2025, reflecting steady enterprise adoption. Because the discount rate reflects the buyer's credit rather than the supplier's, suppliers often access cheaper capital than they could through their own bank. Furthermore, participation is optional for each invoice, which gives suppliers control over when to accept early payment.
Consider the operational benefits reverse factoring brings to a B2B relationship:
- Suppliers receive payment within 24 to 48 hours of buyer invoice approval.
- Buyers extend their payment terms without damaging supplier relationships.
- Commercial financing costs align with the buyer's stronger credit profile.
- Programs run on digital platforms that integrate with buyer AP workflows.
As a result, reverse factoring has become a standard tool for large buyers managing supplier networks of 100 or more vendors. See our blog on supplier payment tools for related detail. You can also review the how it works page for adjacent options.
Trade Credit, Trade Credit Insurance, and PO Financing
Trade credit is the informal financing that happens whenever a supplier ships goods before receiving payment. Estimates put global trade credit volume in the trillions, making it one of the largest sources of business capital worldwide. Meanwhile, trade credit insurance protects sellers against buyer nonpayment on those extended terms.
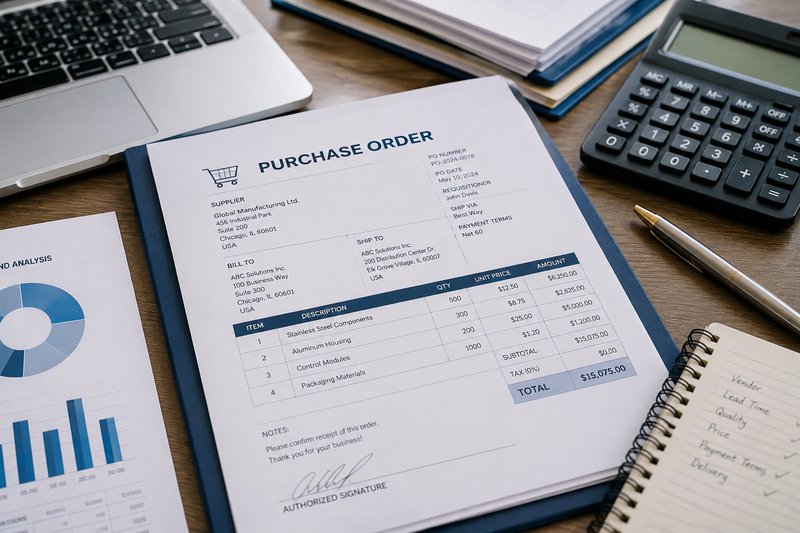
Purchase order (PO) financing sits alongside trade credit for suppliers who need cash to fulfill large orders before invoicing. The lender pays your supplier directly so you can produce or procure the goods, and then collects from your customer once the invoice is paid. Advance rates typically cover 70 to 100 percent of supplier costs depending on the customer's credit and the order profile.
Consider the situations where PO financing outperforms other commercial financing tools:
- Large anchor customer orders that exceed your normal working capital capacity.
- Seasonal spikes requiring inventory buys 60 to 90 days before revenue arrives.
- New buyer relationships where the order size stretches your current supplier terms.
- Government or enterprise contracts with strict delivery timelines and long payment cycles.
Furthermore, PO financing often pairs with invoice financing to cover both the production and collection phases. Review the seller page for tools designed around supplier working capital.
Buyer Funded Early Pay and Dynamic Discounting

Buyer-funded early pay lets a buyer offer suppliers accelerated payment at a small discount, funded from the buyer's own cash or a partner platform. Dynamic discounting works on a sliding scale, where the discount shrinks as the invoice ages toward its original due date. Both models improve supplier cash flow while giving the buyer either a discount or a rebate.
Unlike reverse factoring, buyer-funded early pay does not require a third-party financier when the buyer has excess cash. Meanwhile, platform-based versions add a virtual procurement card so the buyer extends terms and still pays the supplier early. Non-recourse structures also mean the platform absorbs buyer nonpayment risk rather than pushing it back to the supplier.
According to Porter Capital, platforms like these are playing a growing role in helping businesses maintain operational continuity. As a result, mid-market buyers now use early pay as a standard part of their accounts payable stack. Review the electronic payments page for adjacent buyer-side tools.
Building a B2B Commercial Financing Stack That Fits
No single product covers every B2B cash flow need, and stacking the right mix depends on transaction size, customer credit, and existing lender relationships. Term debt covers fixed investments, revolving lines cover general working capital, and receivables or payables tools cover timing gaps. Meanwhile, commercial financing costs vary widely across product categories.
A cleaner stack separates secured and unsecured facilities by purpose so covenants stay intact. Term debt and revolving lines stay with your senior lender, while unsecured early pay handles supplier and receivables timing without triggering subordination work. Furthermore, unsecured tools do not add UCC filings that shrink future borrowing capacity.
Cross-border B2B transactions add currency, customs, and payment friction that push companies toward platform-based tools. Review the international buyer page and the freight broker page for sector examples.
Ready to Structure the Right B2B Financing Stack?
B2B commercial financing works best when each product matches a specific transaction pattern, customer profile, and cost tolerance. Reverse factoring, PO financing, trade credit insurance, and buyer-funded early pay each solve distinct problems that a single line of credit rarely covers. Combining two or three of these tools typically outperforms relying on one broad facility.
Our team helps buyers and suppliers structure working capital that spans domestic and international transactions. We fund invoices without filing UCCs or taking security interests, which keeps your existing lender relationships intact. To review your stack, please book a call with our team for a working capital plan.
