
Working capital shortfalls push many businesses toward two common tools, and asset based lending sits at the center of that conversation. Owners often confuse it with accounts receivable financing because both use business assets to unlock cash. However, the two products differ in structure, cost, control, and the type of borrower each one fits.
Choosing the wrong option can lock up collateral you needed elsewhere or add fees that shrink already thin margins. This guide breaks down how each product works, what they cost, and when one outperforms the other. You will also see where a modern early pay platform can replace either option for supplier heavy businesses.
What Is the Core Difference Between the Two Options?
Asset based lending is a loan or revolving line of credit secured by a pool of business assets. Accounts receivable financing advances cash against unpaid invoices, either as a loan or a true sale of the receivable. The first is a credit facility, while the second is closer to monetizing a single asset class.
How Asset Based Lending Works in Practice
Asset based lending, often shortened to ABL, gives you a revolving line of credit sized to the value of pledged collateral. Lenders assess accounts receivable, inventory, equipment, and sometimes real estate to set a borrowing base. According to Pathward, advance rates typically reach 80 to 90 percent on receivables and 50 percent or less on inventory.
The lender files a UCC lien on the pledged assets and monitors them through borrowing base certificates, field exams, and periodic audits. Meanwhile, you keep customer relationships and continue collecting invoices in your own name. Reporting requirements grow heavier as facility size increases, and covenants often govern leverage and liquidity.
Consider the following traits when weighing an asset based lending facility:
- Revolving structure that lets you borrow, repay, and redraw as receivables and inventory turn.
- Blended collateral pool covering multiple asset classes under one agreement.
- Lower rates than factoring, though monitoring fees, audit costs, and unused line fees add up.
- Best fit for established borrowers with $10 million or more in eligible collateral.
For context, direct lending now represents 36 percent of total private credit as of March 2024, up from 9 percent in 2010, according to Qubit Capital. That shift reflects steady demand for asset-backed structures across the middle market. You can review adjacent working capital options on our services page to compare fit.
How Accounts Receivable Financing Works Alongside Asset Based Lending
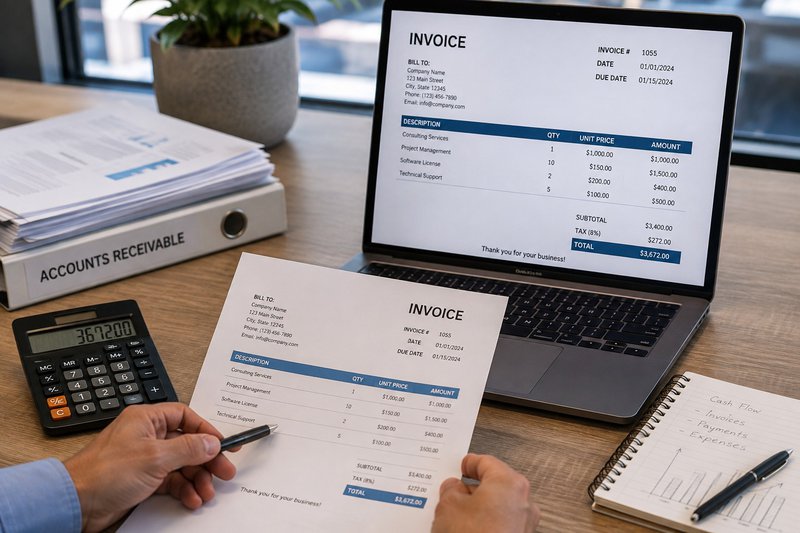
Accounts receivable financing focuses on one asset class, the unpaid invoices your customers owe you. In a factoring arrangement, you sell invoices to a third party at a discount and receive an immediate advance, usually 80 to 90 percent of face value. The buyer remits the full invoice amount to the financing company, which then releases the remainder minus a fee.
There are two main variants you should distinguish before signing:
- Invoice factoring, which involves selling the receivable and often shifts collections to the factor.
- Invoice discounting, which keeps collections with you and treats the advance as a confidential loan.
Fees generally run 1 to 3 percent per invoice cycle, and funding can arrive within 24 to 48 hours. Recourse terms decide who eats the loss if a customer fails to pay, so read those clauses closely. As a result, receivables financing tends to fit fast growing companies, seasonal businesses, and firms that cannot meet bank covenants for a full asset based lending line.
Unlike asset based lending, receivable financing does not usually require broad UCC filings on your entire balance sheet. Instead, the lien attaches to the specific invoices funded. That narrower scope preserves your ability to pledge inventory or equipment elsewhere.
Cost, Speed, and Control Trade Offs
Asset based lending generally carries lower headline rates because the collateral pool is broader and the borrower profile is stronger. Meanwhile, accounts receivable financing prices in the operational work of verifying, funding, and collecting each invoice. A 2024 survey cited by State Financial found that 65 percent of businesses using ABL reported improved cash flow stability.
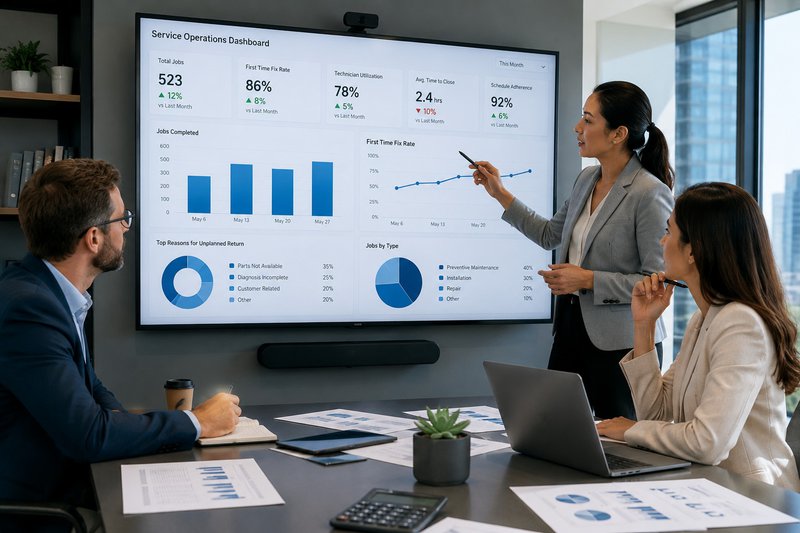
Speed favors receivables financing on day one, with funding often available within two business days of onboarding. Asset based lending takes longer to close because of appraisals, field exams, and legal work, though renewals move faster. Control also splits along product lines, since factoring can put a third party in front of your customers.
Consider these decision points when weighing cost against control:
- Volume of eligible receivables and whether inventory or equipment adds meaningful collateral.
- Customer concentration, since lenders discount heavily when one buyer dominates your book.
- Willingness to accept UCC filings, covenants, and quarterly audits.
- Whether early pay from customers could replace debt entirely.
For a deeper look at fraud risk that affects both products, see our blog on protecting receivables. Additionally, review the about section to see how our platform compares.
Where Early Pay Replaces Traditional Financing
Both asset based lending and accounts receivable financing solve the same underlying problem, waiting 30, 60, or 90 days for payment. However, they solve it by adding debt or by selling a receivable at a discount. An unsecured early pay program lets your customer approve the invoice and pushes payment to you within 24 hours.
Because the buyer funds the discount, there is no UCC filing on your assets and no monthly loan payment. Furthermore, you keep credit lines open for growth, inventory buys, or equipment upgrades. Suppliers who serve mid market and enterprise buyers often find this path cheaper than a traditional asset based lending facility.
You can read more about the mechanics on our electronic payments page and see international use cases on the international buyer page.
Ready to Compare Your Financing Options?
Choosing between asset based lending and accounts receivable financing depends on collateral, cost tolerance, and how much control you want to keep over customer relationships. A quick review of your invoice aging, customer mix, and existing debt covenants will point you toward the right structure. In many cases, a hybrid approach or an early pay program produces better economics than either standalone product.
Our team can walk you through the numbers and show you where an unsecured early pay solution fits alongside your current lender. We work with domestic and international suppliers, freight brokers, and mid market buyers across the United States and Canada. To start the conversation, please contact our team today for a working capital review.
